Translating a legacy manual workflow into a streamlined, fully digital experience. By tackling market-specific challenges and balancing business needs for accelerated approvals and improved transparency.
At a Glance
TL;DR
Over 80% of India's urban housing market is driven by large multistory apartment projects — hundreds of units per property, multiple developers, thousands of customers, all moving through the same loan pipeline.
- [ 1.1 ]
HDFC's existing system wasn't built for this. It was built for single-unit listings, and it showed. Loan applications moved through a patchwork of agents, spreadsheets, and legacy screens.
- [ 1.2 ]
The opportunity: build a fully digital workflow that eliminates agent dependency, reduces processing time, and scales with growing loan volume.
- [ 1.3 ]
Provides loan visibility, transparency, and trust for users and business owners.
What 30 Days of Silence Actually Looks Like
Problem
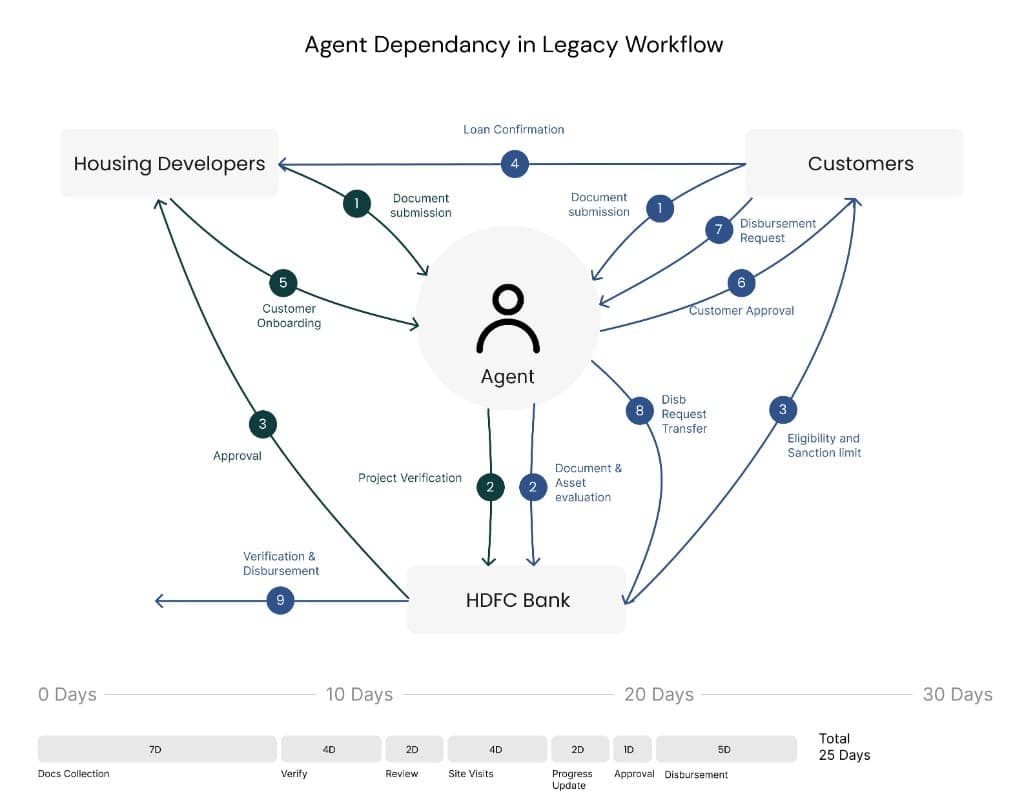
Agent-dependent, 30-day pipeline
Tension ·Visibility vs. control
Solution
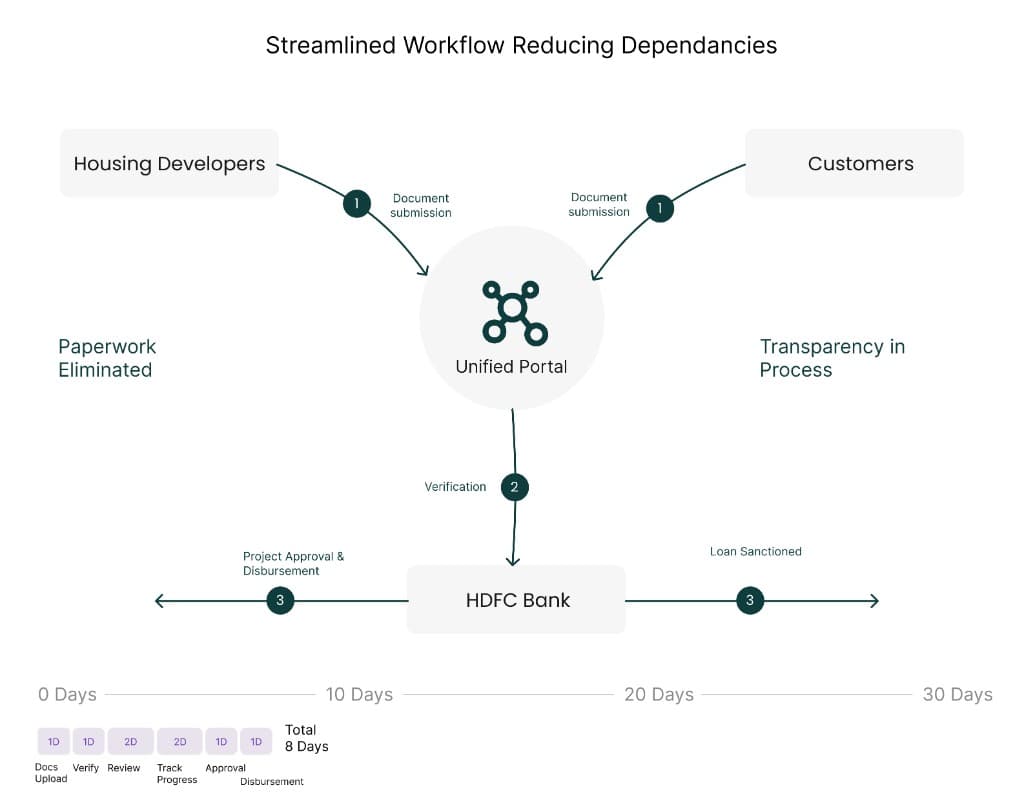
One unified digital portal
Tension ·Automation vs. compliance
- Problem
- A developer submits documents through an agent. The agent forwards them to the bank. Somewhere inside, the application enters a queue no one outside can see. Days pass. The developer calls the agent. The agent calls the bank. Nobody has a clear answer. More days pass. A document is missing — but no one told the developer, so they're still waiting. By the time the correction is made, weeks have gone by.
- Solution
- A Unified Portal connects Housing Developers and Customers to HDFC Bank, with verification, approval, and disbursement steps completing on an 8-day timeline.
Field Research
Six cities, one pattern
- Who we talked to
- We interviewed housing developers across six cities — Mumbai, Delhi, Bangalore, Chennai, Hyderabad, and Pune — ranging from boutique developers with two ongoing projects to firms managing hundreds of units simultaneously.
- Language Barriers
- Mid level developers face language barriers and low comfort with digital tools.
- Reliance on Agents
- This dependency suggests the existing ecosystem doesn't meet user needs.
- Transparency in Status
- Users experience frustration due to absence of direct visibility into loan status.
Market & Competitors
Gaps & opportunities
- Market Analysis
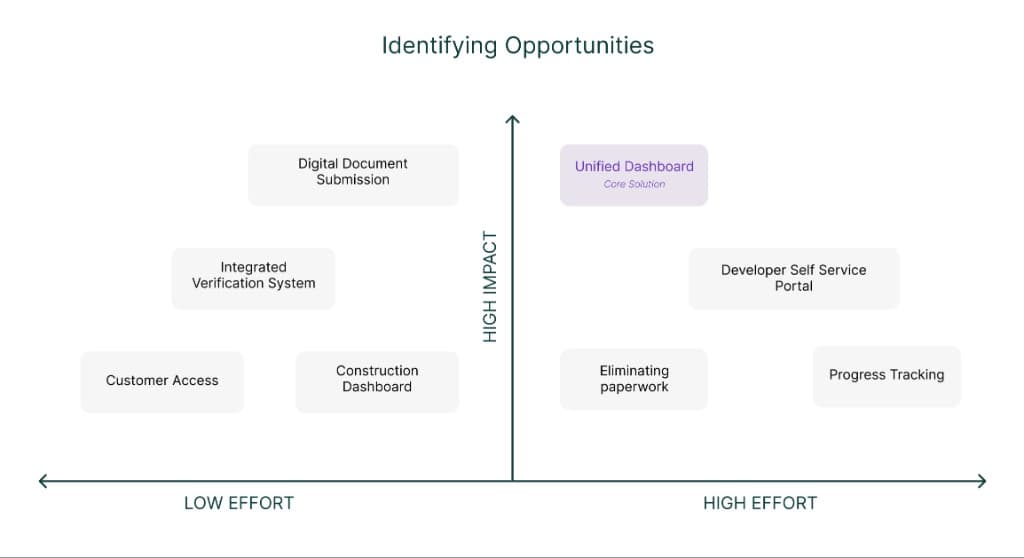
- India's urban housing market is dominated by large multistory apartment projects (over 80%) involving hundreds of units per property.
- Competitor Benchmark
- Other banks relied on manual Excel-based data entry, increasing risk of errors. Real Estate platforms like MagicBricks and NoBroker optimized end-user browsing but lacked enterprise onboarding workflows.
Seven Teams. Seven Agendas. One Product.
Each department (Credit, Legal, Technical, Disbursement) wanted their own data fields and forms to ensure complete information capture and accountability. Customers and relationship managers wanted to avoid filling or uploading the same information repeatedly during the loan journey.
The business wanted strict audit trails and manual checkpoints before releasing funds to developers to ensure compliance with RBI and internal audit norms. Developers wanted faster disbursement processing once milestones were achieved, avoiding manual back-and-forth.
Departments wanted control over when status updates were visible externally to avoid premature disclosure of internal decisions. Customers wanted real-time updates to reduce uncertainty and constant follow-ups.
Ideation
Proposed Workflow
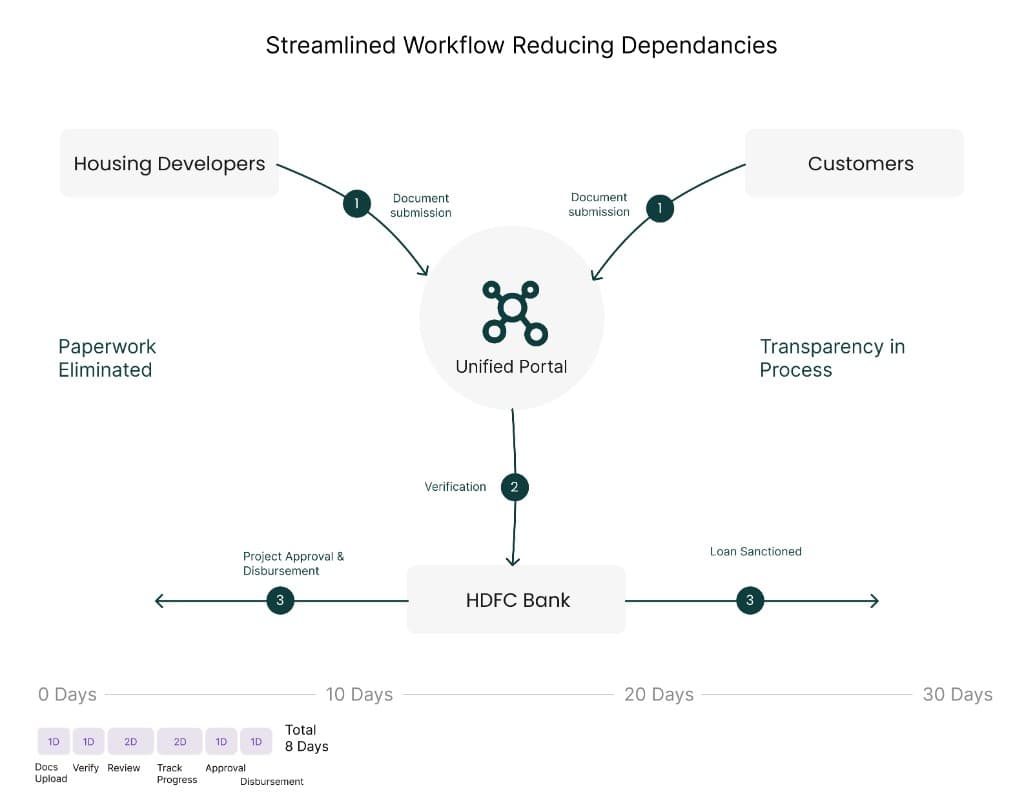
- For HDFC
- Central underwriting queue with SLA tracking · Role-aware approvals and escalation paths · Integrated risk flags with audit trails · Dashboards for disbursement KPIs across regions · Batch exports for treasury and reconciliation
- For Customers
- Transparent application timelines · Digital document submission and previews · Status notifications via SMS/email · Self-help checklist for prerequisites · Mobile-responsive journey for co-applicants
- For Developers
- Portfolio view of towers and disbursement stages · Offline-friendly site progress capture · Shared document vault with versioning · Comment threads anchored to approvals · Export handoffs to compliance reviewers
Design Philosophy
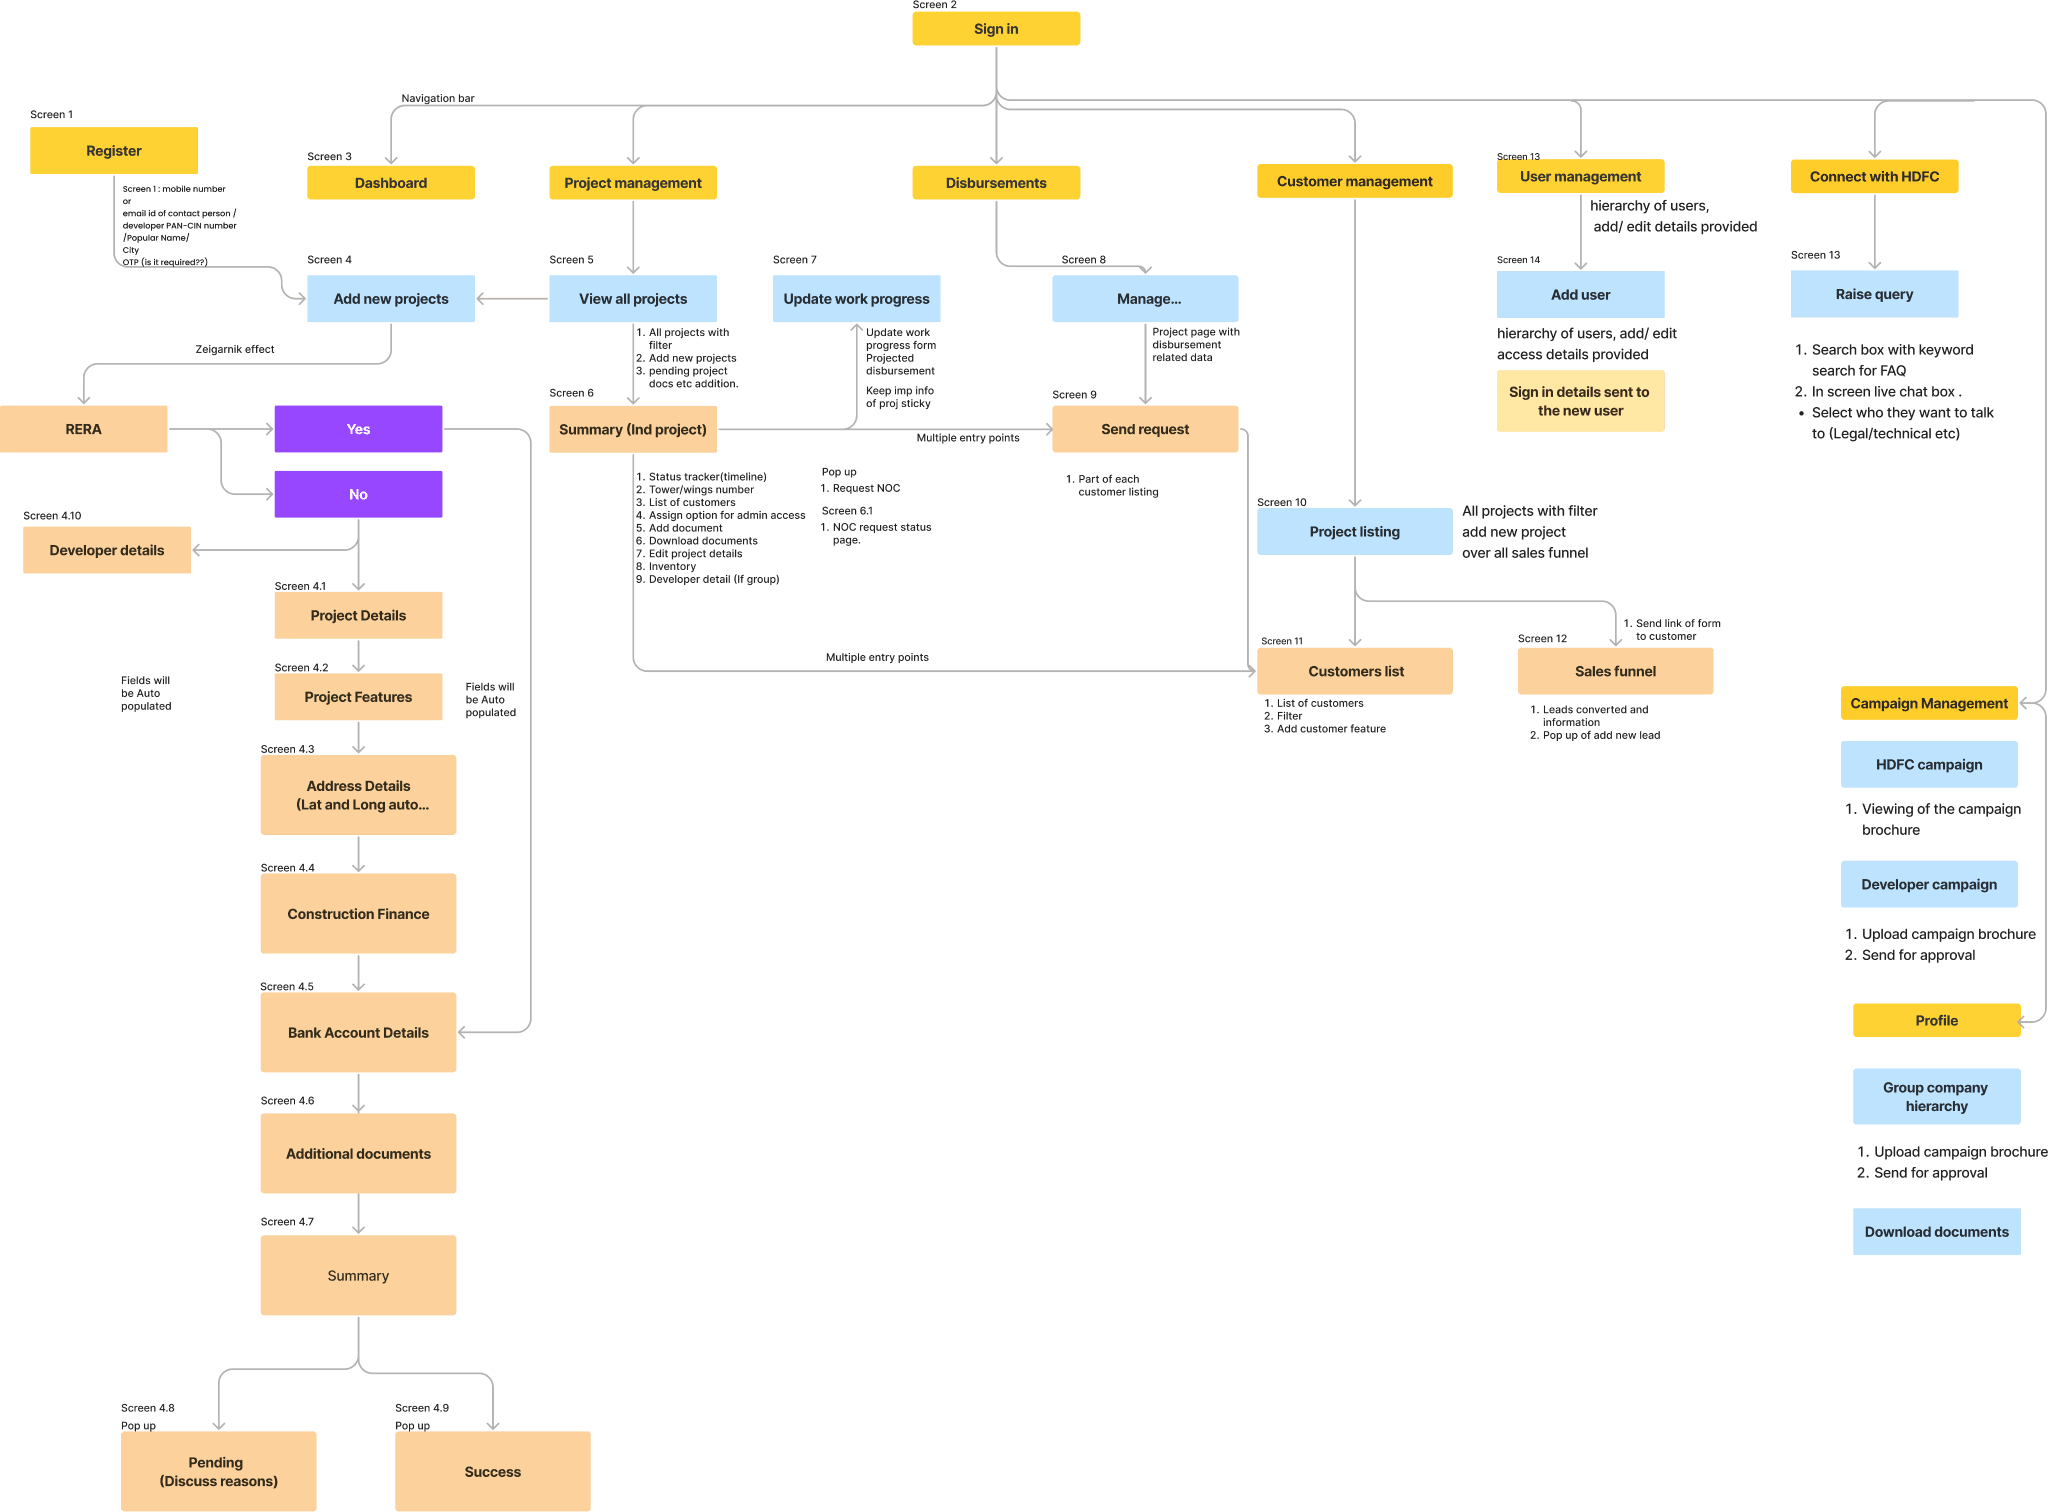
Reduced workflow steps through guided paths, dashboards, and inline validation so analysts spend time on judgment, not data wrangling.
Clear status timelines, disclosures, and feedback patterns so borrowers and developers understood where they stood.
Component-based patterns and repeatable templates adapted as new projects and corridors onboarded.
Kept HDFC analysts, borrowers, builders, and field teams united in shared objects and statuses.
Planned offline edge cases and exception flows so disruptions did not deadlock disbursement.
Plain-language copy, multilingual consideration, and legible hierarchies lowered barriers for junior staff and borrowers.
Final Designs
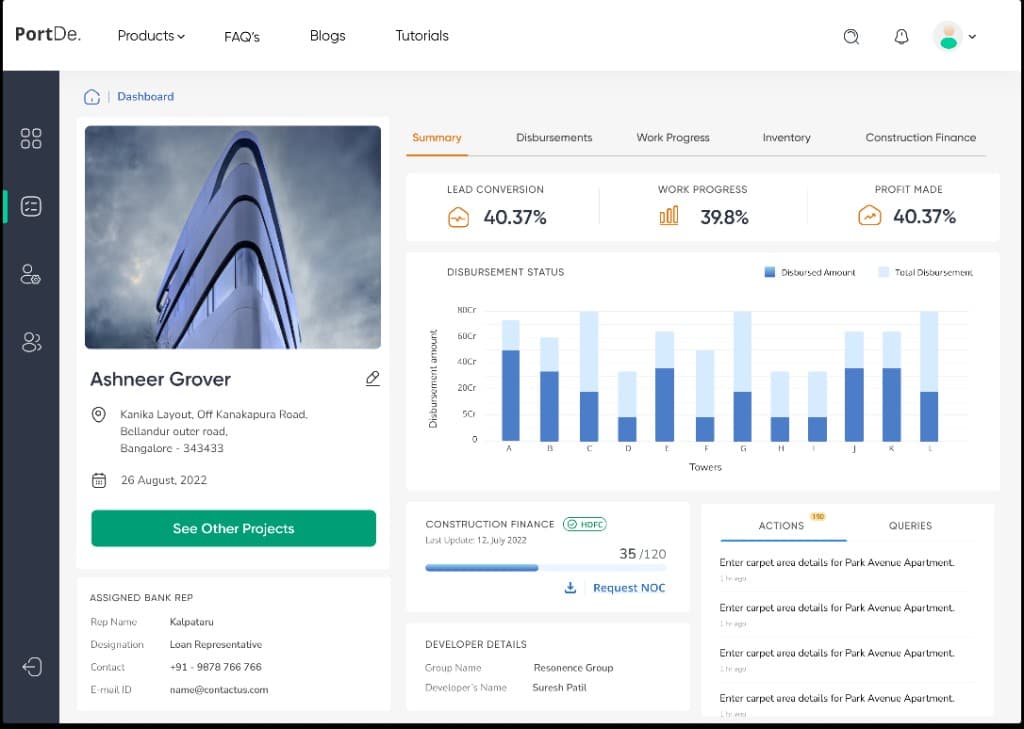
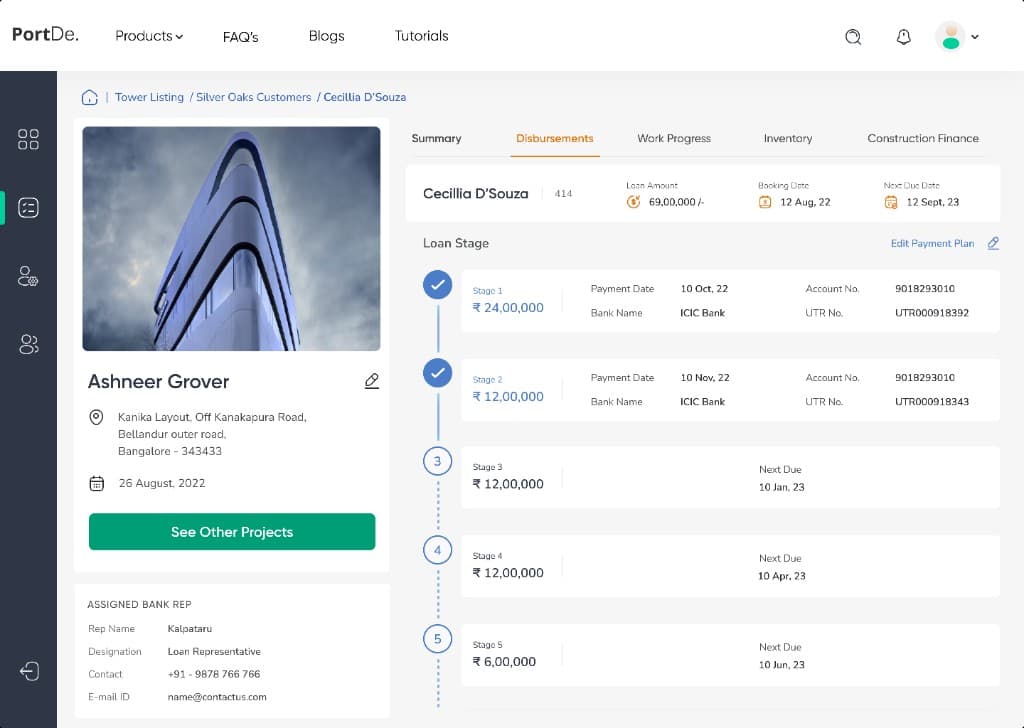
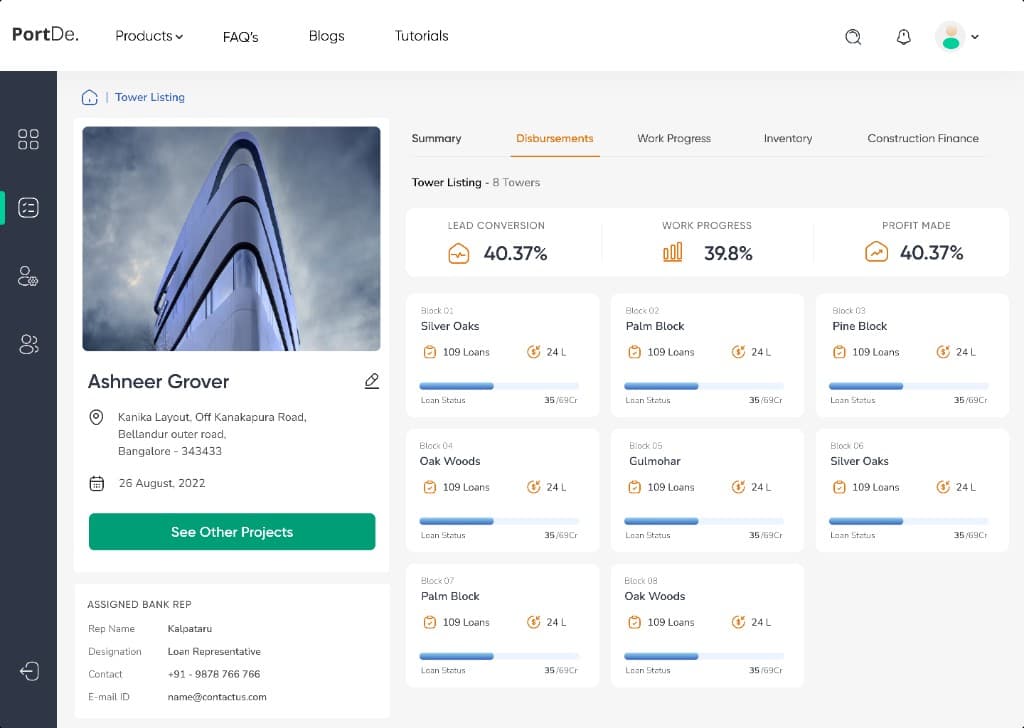
Project Listing
Users can view projects and locate them on a map — surfacing approvals, timelines, and project health at glance.
Shipped flows for project discovery, disbursement requests, and construction progress — readable and actionable for developers, analysts, and borrowers.
Outcomes & Learnings
What worked, what I'd change
- What worked
- Embedding early checkpoints with underwriting led to tighter feedback loops. Transparent milestones reduced inbox escalations. Shared component library aligned dev and QA handoffs.
- What I'd do differently
- Probe regional branch variations sooner in rollout planning. Instrument analytics earlier to validate KPI adoption dashboards. Expand multilingual pilot coverage for tier-3 cities earlier.
- By the numbers
- 8 months in the making, with 7+ stakeholder teams aligned. 500K+ users onboarded inside the first operational year, and a 30% increase in loan volume.